What a winning financial plan for Syrian refugees reveals about planning beyond the numbers
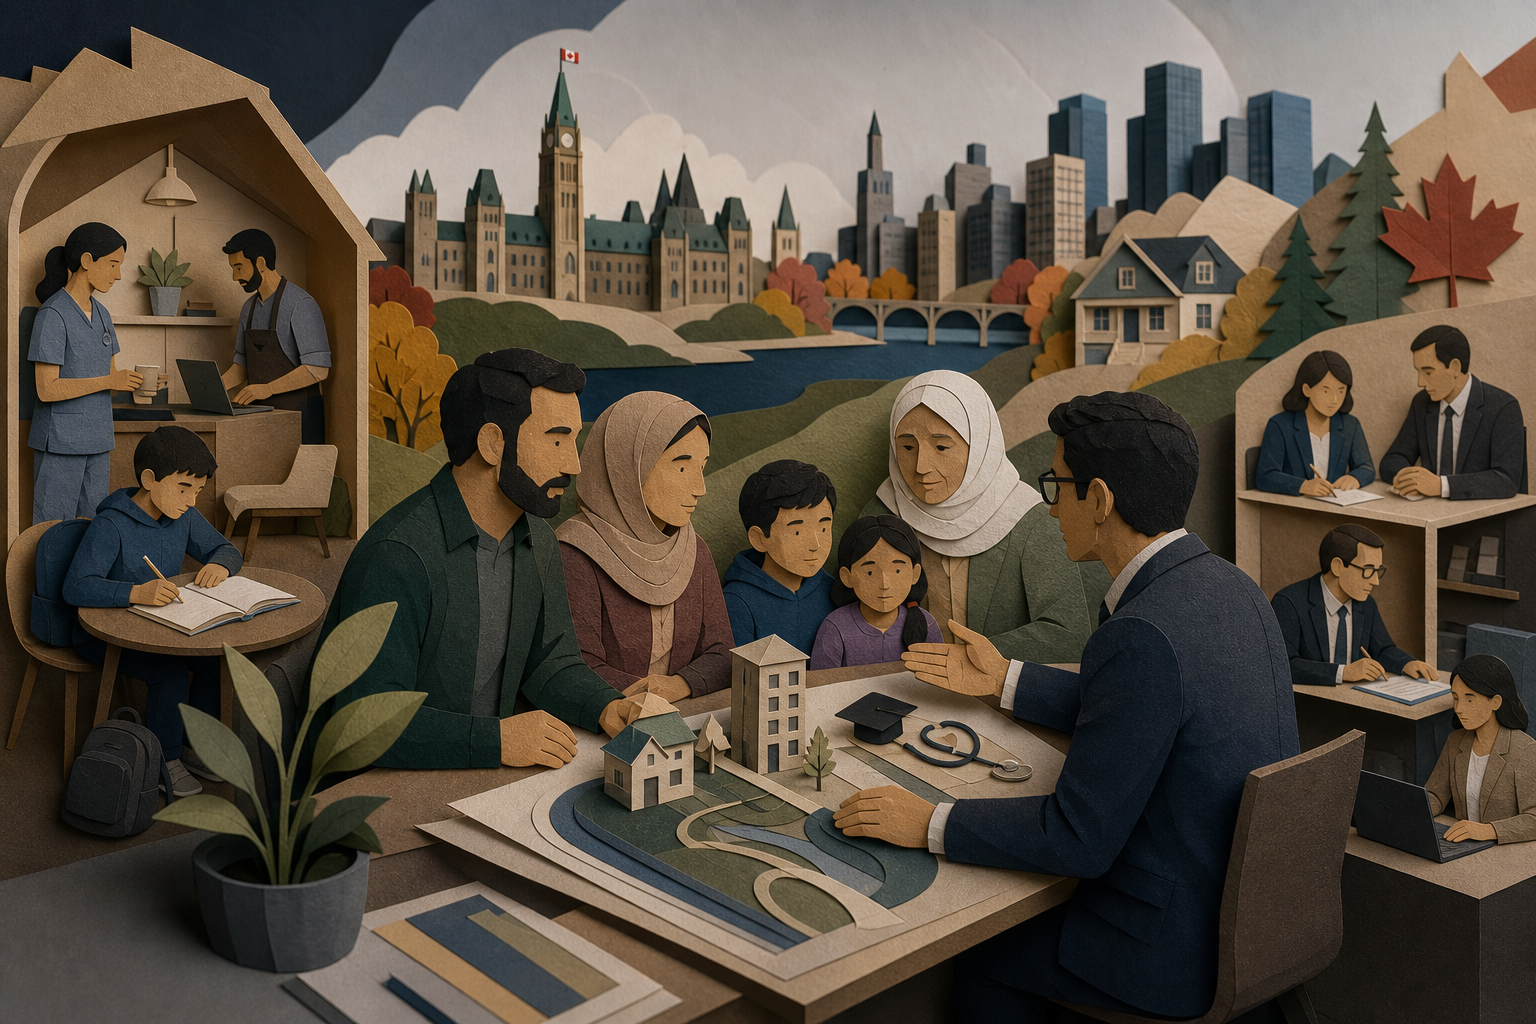
Louai Bibi built his hypothetical clients from memory. A Syrian refugee couple in their early forties, one working in healthcare, the other starting a small business. Three children in different stages of schooling. A grandmother joining them from overseas. Assets that included TFSA room, new RRSP contribution history, and a rental property back home they couldn't easily access. The case study he submitted to FP Canada's 2024 Plan of the Year competition wasn't fiction dressed up as planning, it was the compressed reality of dozens of conversations he'd had in Ottawa's refugee community, now structured into a single comprehensive file.
He won. The award, judged against the highest technical standards in the Canadian planning profession, went to a plan that succeeded not because of exotic tax strategies but because it treated emotional complexity as a variable worth modeling.
Why the competition structure matters
FP Canada's Plan of the Year requires entrants to solve multi-generational financial problems under observation. The judges, senior CFP professionals, evaluate whether the planner integrates retirement projections, tax optimization, estate planning, and risk management into a single cohesive structure. Most submissions demonstrate technical competence. The ones that win demonstrate something harder: they show how a plan holds together when the client's actual life intervenes.
Bibi's case included elements that don't fit neatly into planning software. The grandmother's sponsorship created a dependency claim that affected the couple's tax picture and their estate documents. The rental property in Syria existed on paper but generated no reliable income and couldn't be sold without traveling back, which the family wasn't willing to do. The couple's risk tolerance was shaped not by a questionnaire but by having rebuilt once already. Planning for them meant acknowledging that the standard 60/40 portfolio allocation assumes a stability they hadn't experienced.
What "complex and intimate" actually means
The term FP Canada used to describe the winning entry, complex and intimate, names the gap most plans fail to close. Complexity in financial planning usually refers to the number of accounts, the layers of corporate structure, or the tax implications of a business sale. Intimacy refers to something different: whether the plan reflects what the client would actually do under pressure.
A planner can model a 3.5% withdrawal rate over 30 years with Monte Carlo simulations and arrive at a portfolio that survives 87% of historical sequences. That's complexity. The intimacy question is whether the client would stick with the plan through a 40% drawdown in year three, or whether they'd liquidate at the bottom because their prior experience taught them that institutions collapse and cash is the only reliable asset. Bibi's case study succeeded because it built the latter reality into the former structure.
What this signals about the profession
Seventeen thousand CFP professionals practice in Canada, yet only 20% of Canadians have a written financial plan. The gap exists partly because the public remains confused by designation proliferation, CFP, QAFP, CFA, PFP, and partly because many people assume planning is reserved for those with portfolios above $500,000. The FP Canada award pushes in the opposite direction. It validates that the hardest planning problems are often the ones involving lower net worth but higher human complexity.
The 2024 capital gains inclusion rate change, the revised Alternative Minimum Tax rules, Ontario's title protection legislation, these shifts demand technical fluency. But they don't require empathy. Bibi's win suggests the profession is realizing that a plan built entirely on technical fluency, no matter how precise, fails if the client doesn't believe it.
The result is less a shift in tools than a shift in what gets weighted. A planner who can name the exact marginal tax rate on eligible dividends is table stakes. A planner who can model how a family's relationship with debt changes after fleeing a war is rare.